


A random matrix is a matrix of given type and size whose entries are random variables with a specified joint statistical distribution.
Random matrix theory is cited as one of the "modern tools" used in Catherine's proof of an important result in number theory in the 2005 film Proof.
For a real matrix of size  , where
 is a positive integer,
with independent entries having a
standard normal distribution, the
expected number of real eigenvalues is given by
 |  |  |
(1)
|
 |  |  |
(2)
|
where  is a hypergeometric function and
 is a beta
function (Edelman et al. 1994, Edelman and Kostlan 1995).
 has asymptotic behavior
 |
(3)
|
Let  be the probability that there are exactly
 real eigenvalues
in the complex spectrum of the
 matrix. Edelman (1997) showed
that
 |
(4)
|
where  unless
 and
 is even. For
 ,
the full probability function
for the number of real eigenvalues
was derived by Kanzieper and Akemann (2005) as
 |
(5)
|
where
 |  |  |
(6)
|
 |  |  |
(7)
|
The sum runs over all partitions  of size
 , where
 is the number of pairs of complex-conjugate eigenvalues, and
 is a zonal polynomial.
The frequency representation
 has
 distinct parts
 , with respective multiplicities
 , and
 (Kanzieper and Akemann 2005). The arguments
 depend on the parity of
 (the matrix dimension) and are given by
 |
(8)
|
where  is a positive integer,
 is a matrix trace, and
 is an
 matrix with entries
 |  |  |  |  | ![+2y^2L_(2alpha-1)^(2(beta-alpha)+1)(-2y^2)]dy](/images/equations/RandomMatrix/Inline45.svg) |
(9)
|
 |  |  |
(10)
|
where  and
 vary between 0 and
 and
 ,
with
 the floor function. The extra column
 used for odd
 is evaluated by the same integral formula. Here,
 are generalized Laguerre
polynomials, with
 ,
and
 is the erfc, the complementary error function (Kanzieper
and Akemann 2005).

For  ,
Edelman (1997) proved that the density of nonreal eigenvalues
 in the upper
half-plane of such a matrix is
 |  |  |
(11)
|
 |  |  |
(12)
|
for  ,
where
 is the erfc (complementary error) function,
 is the exponential
sum function, and
 is the upper incomplete gamma function.
The integral of
 over a region is the expected
number of eigenvalues there. Integrating over
the upper half-plane (and multiplying by 2) gives
the expected number of nonreal eigenvalues
as
 |  |  |
(13)
|
 |  |  |
(14)
|
 |  |  |
(15)
|
where  is a regularized hypergeometric
function (Edelman 1997). The first few values are
 |  |  |
(16)
|
 |  |  |
(17)
|
 |  |  |
(18)
|
 |  |  |
(19)
|
 |  |  |
(20)
|
(OEIS A052928, A093605, and A046161).
Girko's circular law implies that if  is chosen uniformly from the eigenvalues
of such a matrix, then
 converges in distribution to the uniform
distribution on the unit disk in the complex
plane as
 (Edelman 1997, p. 209).
Wigner's semicircle law states that the limiting statistical distribution of
the eigenvalues of a Wigner
matrix with off-diagonal entry variance
1, scaled by  ,
is the semicircular distribution (Tao
2010).
If  matrices
 are chosen independently with probability
1/2 from each of
 |  |  |
(21)
|
 |  |  |
(22)
|
then, with probability one,
 |
(23)
|
where 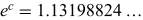 (OEIS A078416) and
 denotes the matrix spectral
norm (Bougerol and Lacroix 1985, pp. 11 and 157; Viswanath 2000). The value
 is the constant
appearing in the random Fibonacci sequence.
The following Wolfram Language code
can be used to estimate
 ,
rescaling after each multiplication to avoid numerical overflow.
With[{n = 100000},
 Exp[
 Last[
 Fold[
 Function[{state, sign},
 Module[{m, scale},
 m = state[[1]] . {{0., 1.}, {1., sign}};
 scale = Norm[m, 2];
 {m/scale, state[[2]] + Log[scale]}
 ]
 ],
 {N[IdentityMatrix[2]], 0.},
 RandomChoice[{-1, 1}, {n}]
 ]
 ]/n
 ]
 ]
For random real symmetric matrices, Liang et al. (2026) proved a uniform matrix rank
bound under a bound on point probabilities.
Let  be an
 random real symmetric matrix whose entries
above the diagonal are independent
and have every point probability at most a fixed
 . The diagonal entries may
be jointly dependent, but their joint vector is independent of the off-diagonal entries.
There is a constant
 such that
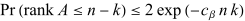 |
(24)
|
for  .
No moment, centering, or identical-distribution assumption
is imposed. Liang et al. (2026) report AI assistance in checking and refining
technical details of the proof.

 ." In
 Real Eigenvalues, Related Distributions, and the Circular
Law." J. Multivariate Anal. 60, 203-232, 1997.