

Glauber dynamics is a Markov process that updates one spin at a time and preserves a specified Gibbs measure.
In the heat-bath version, each site's rate-one clock replaces its spin by a sample
from the conditional Gibbs measure given all other
spins. For  sites, its generator is
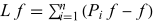 , where
 is conditional averaging at site
 . The discrete-time version chooses a uniform site at each
attempted update. Its transition matrix is
 , so
 . Time measured in attempted updates is therefore
 times the rate-one-per-site time scale.
Glauber Dynamics
See also
Autocorrelation, Gibbs Measure, Markov Chain, Markov Chain Cutoff, Mixing Time, Spectral GapExplore with Wolfram|Alpha

References
Levin, D. A. and Peres, Y. Markov Chains and Mixing Times, 2nd ed. With contributions by E. L. Wilmer. Providence, RI: American Mathematical Society, 2017. https://doi.org/10.1090/mbk/107.Cite this as:
Weisstein, Eric W. "Glauber Dynamics." From MathWorld--A Wolfram Resource. https://mathworld.wolfram.com/GlauberDynamics.html