

Autocorrelation of a real-valued stochastic process  measures the correlation of values separated by a
given lag. For a weakly
stationary process with mean
 , the autocovariance
and autocorrelation functions are
 |  |  |
(1)
|
 |  |  |
(2)
|
where  denotes the expectation value of
 and
 is assumed when defining
 . They depend only on the lag
 , not on the time
 . Their sample counterpart is the sample
autocorrelation.
For a finite sequence whose indices are taken modulo its length, the corresponding notion is periodic autocorrelation. The non-wrapping counterpart is aperiodic autocorrelation.
For a square integrable complex function  ,
the autocorrelation is defined by
 |  |  |
(3)
|
 |  |  |
(4)
|
where  denotes cross-correlation and
 is the complex conjugate
(Bracewell 1965, pp. 40-41).
Note that the notation  is sometimes used for
 and that the quantity
 |
(5)
|
is sometimes also known as the autocorrelation of a continuous real function  when the limit exists (Papoulis
1962, p. 241).
The autocorrelation discards phase information, returning only the power, and is therefore an irreversible operation.
There is also a somewhat surprising and extremely important relationship between the autocorrelation and the Fourier transform
known as the Wiener-Khinchin theorem.
Let =F(omega)](/images/equations/Autocorrelation/Inline27.svg) ,
and
 denote the complex conjugate of
 , then the inverse
Fourier transform of the absolute square of
 is given by
=int_(-infty)^inftyf^_(tau)f(tau+t)dtau.](/images/equations/Autocorrelation/NumberedEquation2.svg) |
(6)
|
For the square integrable complex function  ,
Schwarz's inequality gives
|<=int_(-infty)^infty|f(tau)|^2dtau=[f*f](0).](/images/equations/Autocorrelation/NumberedEquation3.svg) |
(7)
|
Thus its complex modulus is maximum at the origin. For a square
integrable real function  ,
 itself is maximum at the origin; in other words,
 |
(8)
|
To see this, let  be a real number. Then
 |
(9)
|
 |
(10)
|
 |
(11)
|
Define
 |  |  |
(12)
|
 |  |  |
(13)
|
Then the preceding inequality is  for every real
number
 .
If
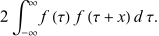 ,
the result is immediate. If
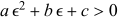 , the discriminant satisfies
 , so
 and hence
 . It follows that
 |
(14)
|
with the equality at  .
This proves that
 is maximum at the origin.
