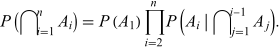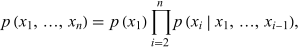The probability chain rule expresses the probability of an intersection of events as a product
of successive conditional probabilities.
For events  with
 and
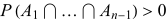 ,
No assumption of independence is required.
For discrete random variables, the corresponding factorization of the joint probability mass
function is
provided the conditioning histories have positive probability. This follows by repeatedly applying the definition of conditional
probability. Taking logarithms and expectations
gives the entropy chain rule (Cover and Thomas
2006, Ch. 2).
See also
Chain Rule,
Conditional Probability,
Entropy Chain Rule,
Joint
Distribution,
Probability,
Probability
Mass Function,
Random Variable
Explore with Wolfram|Alpha
References
Cover, T. M. and Thomas, J. A. Elements of Information Theory, 2nd ed. Hoboken, NJ: Wiley, Ch. 2, 2006.Papoulis,
A. "Conditional Probabilities and Independent Sets." §2-3 in Probability,
Random Variables, and Stochastic Processes, 2nd ed. New York: McGraw-Hill,
pp. 33-45, 1984.
Cite this as:
Weisstein, Eric W. "Probability Chain Rule."
From MathWorld--A Wolfram Resource. https://mathworld.wolfram.com/ProbabilityChainRule.html
Subject classifications