

The joint distribution of random variables  assigns probabilities
to events involving the variables simultaneously. For two
real-valued random
variables, it is determined by the joint
distribution function
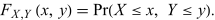 |
In the discrete case, the joint probability mass function is 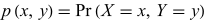 .
In the continuous case, when a joint probability
density function
 exists, probabilities are integrals
of
 over Borel subsets of the Euclidean
plane. Summing or integrating
out variables gives the marginal distributions.
A finite compatibility question can be expressed geometrically. Given real numbers  ,
 ,
 ,
and
 ,
there are jointly distributed random variables
 ,
 , and
 taking values in
 with
 ,
 ,
 , and
 iff
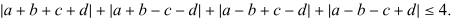 |
Here the brackets denote expectation values. The eight deterministic vectors 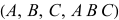 are the four mutually orthogonal vectors
 ,
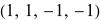 ,
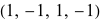 , and
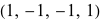 and the four vectors
obtained by multiplying them by
 . Their convex hull is a four-dimensional
cross polytope. Expressing
 in the orthogonal
basis formed by the four listed vectors gives the
displayed condition. In particular, no such distribution has
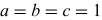 and
 . This is a probability formulation of the compatibility
constraints used in the Greenberger-Horne-Zeilinger
theorem (de Barros and Suppes 2000, Trott 2006).
