

The entropy chain rule expresses the joint entropy of random variables as a sum
of conditional entropies. For discrete random variables  with finite alphabets and logarithm
base
 ,
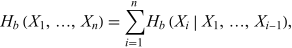 |
where the first term is  . The identity
follows from the probability chain rule
by taking the negative expectation value of
the logarithm of the joint probability
mass function (Gray 1990, p. 41).
There is also a chain rule for relative entropy. For joint probability mass functions  and
 on finite alphabets, with
 wherever
 ,
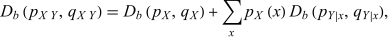 |
where the marginal distributions are denoted by  and
 , and the conditional
distributions given
 by
 and
 . Terms with
 are omitted. Related decompositions for mutual
information follow by applying the entropy chain rule to
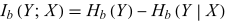 (Cover and Thomas 2006, pp. 21-25).
