

A moment is a sum or integral of a power of a quantity, often taken with respect to a statistical
distribution. The  th
raw moment
 (i.e., moment about zero) of a distribution
 is defined by
 |
(1)
|
where
 |
(2)
|
 , the mean, is usually
simply denoted
 . If the moment is instead
taken about a point
 ,
 |
(3)
|
A statistical distribution is not uniquely specified by its moments, although it is by its characteristic function.
The moments are most commonly taken about the mean. These so-called central moments are denoted  and are defined by
 |  |  |
(4)
|
 |  |  |
(5)
|
with  . The second moment about the mean
is equal to the variance
 |
(6)
|
where  is called the standard
deviation.
The related characteristic function is defined by
 |  |  |
(7)
|
 |  |  |
(8)
|
The moments may be simply computed using the moment-generating function,
 |
(9)
|
In analytic number theory, moments often sum or integrate powers of the complex modulus.
For example, for a finite family of values  , nonnegative weights
 , and
 , the weighted sum
 is a moment of order
 .
If the weights have positive total, dividing by
 gives an absolute
moment for the corresponding discrete statistical
distribution. A continuous example is the moment of order
 of the Riemann zeta function
along the critical line, commonly written
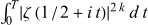 (Soundararajan 2009).
