

The moment-generating function of a real random variable  is defined by
 |
(1)
|
where  denotes the expectation value of
 . Here the moment-generating function is said to exist when
 for
 with some
 .
This definition applies to arbitrary probability
distributions, including discrete distributions.
Existence of a probability density function
is not required.
If  has a probability density function
 ,
then for
 ,
 |  |  |
(2)
|
 |  |  |
(3)
|
 |  |  |
(4)
|
where  is the
 th
raw moment. The power series
can be integrated term by term because its absolute sum
 has finite expectation
value under the stated hypothesis.
For independent random variables  and
 ,
the moment-generating function of their sum satisfies
 |  |  |
(5)
|
 |  |  |
(6)
|
 |  |  |
(7)
|
 |  |  |
(8)
|
Finiteness on  implies that
 is infinitely differentiable
there and that every absolute moment of positive
integer order is finite. Differentiation
under the expectation value gives the following
identities for
 and positive integers
 (Durrett 2019, pp. 106-107):
 |  |  |
(9)
|
 |  |  |
(10)
|
 |  |  |
(11)
|
 |  |  |
(12)
|
 |  |  |
(13)
|
 |  |  |
(14)
|
 |  |  |
(15)
|
 |  |  |
(16)
|
The mean and variance are therefore
 |  |  |
(17)
|
 |  |  |
(18)
|
 |  |  |
(19)
|
 |  |  |
(20)
|
It is also true that
 |
(21)
|
where  is the
 th
central moment,
 , and
 is the
 th raw moment.
It is sometimes simpler to work with the logarithm of the moment-generating function, which is also called the cumulant-generating function, and is defined by
 |  |  |
(22)
|
 |  |  |
(23)
|
 |  | 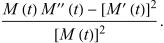 |
(24)
|
But 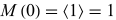 ,
so
 |  |  |
(25)
|
 |  | 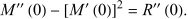 |
(26)
|
