TOPICS
Search

Convergence in Measure


Convergence in measure of a sequence of finite-valued real or complex measurable functions f_n to a finite-valued measurable function f of the same type on a measure space (X,A,mu) means that, for every epsilon>0,

 lim_(n->infty)mu([{x in X:|f_n(x)-f(x)|>epsilon]})=0.

When mu is a probability measure, this is probabilistic convergence.

If mu(X)<infty, almost everywhere convergence implies convergence in measure. The finite-measure hypothesis cannot be omitted in general. On R with Lebesgue measure, let f_n be the characteristic function of [n,n+1]. Then f_n has pointwise convergence to 0, but the measure of {x:|f_n(x)|>epsilon} equals 1 for every 0<epsilon<1 and every n. On an arbitrary measure space, a sequence converging in measure has a subsequence converging almost everywhere to the same function (Viaclovsky 2003, pp. 2-3).
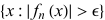


See also

Almost Everywhere Convergence, Convergence, Convergence in Mean, Probabilistic Convergence

Explore with Wolfram|Alpha

References

Viaclovsky, J. "Measure and Integration: Lecture 13." Notes prepared by E. Brown. Cambridge, MA: Massachusetts Institute of Technology, Oct. 16, 2003. https://ocw.mit.edu/courses/18-125-measure-and-integration-fall-2003/8ee188461695d9db958de0347471d0db_18125_lec13.pdf.

Cite this as:

Weisstein, Eric W. "Convergence in Measure." From MathWorld--A Wolfram Resource. https://mathworld.wolfram.com/ConvergenceinMeasure.html

Subject classifications