

Probabilistic convergence, also called convergence in probability, of a sequence of real-valued random variables  to a random variable
 , all defined on a common probability
space, means that, for every
 ,
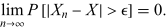 |
The notation  is commonly used. If
 converges almost surely,
then it converges in probability, and convergence in probability implies distributional
convergence. Neither converse holds without additional hypotheses.
For a constant  , distributional convergence to
 also implies convergence in probability to
 (Massachusetts Institute of Technology 2018, p. 12).
The weak law of large numbers is a basic
example of convergence in probability.
A sequence converges in probability to  iff every subsequence
has a further subsequence converging almost
surely to
 (Massachusetts Institute of Technology 2018, p. 4). Convergence
in probability is the special case of convergence
in measure in which the underlying measure is a probability measure.
