A Brownian bridge from  to
 over the time interval
 is a Brownian motion
conditioned to start at
 and end at
 .
If
 is a standard Brownian motion, then a Brownian
bridge with diffusion coefficient
 can be constructed as
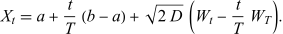 |
(1)
|
It has expectation value and covariance
 |  |  |
(2)
|
 |  | 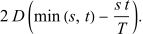 |
(3)
|
In particular,  and
 with probability one, and
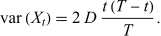 |
(4)
|
Writing  for the transition density of the unconditioned Brownian
motion, the density of the bridge at an intermediate time is
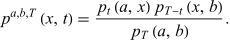 |
(5)
|
This factorization is a special case of the Markov bridge formula. The same conditioned process satisfies the time-inhomogeneous stochastic differential equation
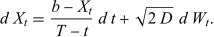 |
(6)
|
This equation holds for  .