

Brownian motion is both the irregular physical motion of microscopic particles suspended in a fluid and a mathematical stochastic process used to model such motion. The name honors the botanist Robert Brown, who observed the phenomenon in 1827 and reported it the following year (Brown 1828). The mathematical term refers to an idealized stochastic process rather than the motion of any particular particle.
A Brownian motion with initial value  is a real-valued stochastic
process
 that satisfies the following properties:
1.  .
2. For all times  , the increments
 ,
 , ...,
 , are independent random variables.
3. For all  ,
 , the increments
 are normally
distributed with expectation value zero
and variance
 .
4. The function  is continuous.
A Brownian motion  is said to be standard if
 .
A geometric Brownian motion is obtained by exponentiating a standard Brownian motion  together with a linear drift. In particular,
 has multiplicative random
changes while
 is a scaled Brownian motion with drift.
Standard Brownian motion has scaling invariance and invariance under time inversion (Mörters and Peres 2010). If  is standard Brownian motion and
 , then
 is also standard Brownian motion. The stochastic
process defined by
 for
 and by 0 at
 is also standard Brownian motion. For Brownian motion starting at
 , these properties apply to the centered stochastic
process
 .
Any Brownian motion
 satisfies a law of large numbers so that
 |
(1)
|
almost surely. Moreover, for every  , a Brownian path
is locally Hölder continuous almost
surely. This means that, on each finite time interval,
there is a random constant
 such that
 |
(2)
|
for all  and
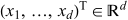 in the interval. On the other
hand, a Brownian path is nowhere
differentiable almost surely.
The above definition is extended naturally to get higher-dimensional Brownian motions. More precisely, given independent
Brownian motions  ,
...,
 which start at
 ,
...,
 ,
one can define a stochastic process
 by
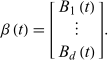 |
(3)
|
Such a  is called a
 -dimensional Brownian motion which starts at
 .
