

The autocovariance of a real-valued stochastic process  between times
 and
 is the covariance between
 and
 , so
 |
where  denotes the expectation value of
 and
 is the population
mean at time
 . For a weakly
stationary process, the mean
is constant and the autocovariance depends only on the lag
 , so it can be written as
 |
The corresponding autocorrelation is 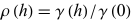 when
 .
