The Laplace functional of a random measure  is the functional
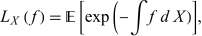 |
where  denotes the expected value; the functional is
defined for suitable nonnegative measurable functions
 . It is called a functional because its
argument is the entire function
 , rather than a number. The Laplace functional generalizes
the Laplace transform of a random
variable and, under standard conditions, determines the probability
law of the random measure. Given a sigma-algebra
 representing available information,
the conditional Laplace functional is the conditional
expectation
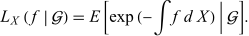 |
It is therefore a random quantity determined by that information; conditioning on an initial state or on an event gives common special cases.