

The conditional expectation of an integrable random variable  on a probability space
 given a sigma-algebra
 is a
 -measurable random
variable, denoted
 , such that
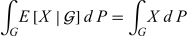 |
for every  .
It is unique up to sets of probability
zero.
For a nonnegative random variable  , the definition extends to conditional expectations
that may take the value
 by the almost-sure increasing
limit
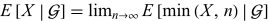 .
Here,
 denotes the minimum.
When conditioning on a random variable  , the notation
 means conditioning on the sigma-algebra
generated by
 . Conditional expectation is the probability-theoretic
analog of averaging while retaining specified information.
