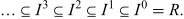TOPICS
Search

Filtration


A filtration is an indexed family of nested mathematical objects. In probability theory, a filtration (F_t)_(t>=0) on a probability space (Omega,F,P) is a nondecreasing family of sigma-algebras satisfying

 F_s subset= F_t subset= F for all 0<=s<=t.
(1)

The sigma-algebra F_t represents the information available by time t. This form of filtration is used in the definitions of a stopping time, martingale, and stochastic integrals.

In algebra, a filtration of ideals of a commutative unit ring R is a sequence of ideals

 ... subset= I_2 subset= I_1 subset= I_0=R,
(2)

such that I_iI_j subset= I_(i+j) for all indices i,j. An example is the I-adic filtration associated with a proper ideal I of R,

 ... subset= I^3 subset= I^2 subset= I^1 subset= I^0=R.
(3)

A ring equipped with a filtration is called a filtered ring.

See also

Associated Graded Module, Associated Graded Ring, Martingale, Probability Space, Rees Module, Rees Ring, Sigma-Algebra, Stopping Time

Portions of this entry contributed by Margherita Barile

Explore with Wolfram|Alpha

References

Doob, J. L. Stochastic Processes. New York: Wiley, 1953.Williams, D. Probability with Martingales. Cambridge, England: Cambridge University Press, 1991.

Referenced on Wolfram|Alpha

Filtration

Cite this as:

Weisstein, Eric W., with contributions by Margherita Barile. "Filtration." From MathWorld--A Wolfram Resource. https://mathworld.wolfram.com/Filtration.html

Subject classifications