

The elephant random walk is a random walk whose next step copies or reverses a uniformly chosen earlier step (Schütz and Trimper
2004). Write  for its steps and
 for its position. Given the first
 steps, choose an index uniformly from 1, 2, ...,
 , independently of the past, and set
 equal to the selected step with copying probability
 , reversing it otherwise. The initial bias is
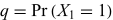 , with
 .
In the superdiffusive regime 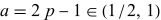 , the normalized
position
 converges almost surely to a limit with a probability
density function. If
 is its density given
 , the density at initial bias
 is
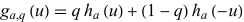 .
Pemmasani (2026) proved that, for each
 , there is
![b_a in (0,1/2]](/images/equations/ElephantRandomWalk/Inline16.svg) such that this density has exactly two local
maxima iff
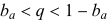 . Outside this
open interval, including its endpoints, it has a unique local maximum.
There is a unique threshold 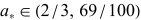 , numerically
about 0.66881, such that
 exactly for
 (Pemmasani 2026). The corresponding copying probability
is
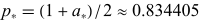 . For the fair start
 , if
 is the positive mode above the threshold, there are
constants
 such that
 |  |  |
(1)
|
 |  |  |
(2)
|
as  . The function
 is continuous, is continuously differentiable above the
threshold, and tends to zero as
 . Its monotonicity over
the whole interval
 remains open.
For every initial bias and every finite number of steps, with  , the distribution of the number of positive
steps has at most two modal plateaus, including possible endpoint modes (Pemmasani
2026). Pemmasani credits Claude with a mathematical strategy for the threshold analysis
and GPT-6 Astra with help resolving a proof gap concerning positivity of
 .
