

An absolutely fair sequence is a sequence of integrable random
variables  ,
 , ... with expectation
value
 and
 |
almost surely for every positive integer  for which
 is defined (Feller 1971). Here the brackets denote expectation
value and conditional expectation,
respectively, and integrable means that
 for every
 . If
 represents the gain on the
 th trial, the condition says that the conditional
expectation of the next gain is zero even after all earlier gains are known.
The partial sums  and
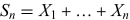 form a martingale,
since
 |
Conversely, if  ,
 , ... is a martingale,
then
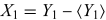 and
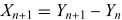 form an absolutely fair sequence, with
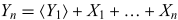 (Feller 1971).
Independent random variables with zero expectation value provide examples. For
instance, independent random variables
taking  and 1 with equal probability give a symmetric one-dimensional random walk through their
partial sums. The gains need not be independent
random variables. If
 and
 are independent
random variables each taking
 and 1 with equal probability,
then the two-term sequence
 ,
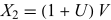 is absolutely fair but dependent. Observing
 forces
 , while
 gives
 or 2.
Zero expectation value for each individual gain is insufficient. If  takes
 and 1 with equal probability and
 for all
 , then
 but
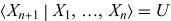 . After the first trial the later
gains are known, so this sequence is not absolutely
fair.
