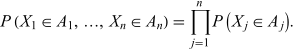TOPICS
Search

Independent Random Variables


Random variables X_1,...,X_n are independent if, for all Borel sets A_1,...,A_n,

 P(X_1 in A_1,...,X_n in A_n)=product_(j=1)^nP(X_j in A_j).

An arbitrary family is independent when every finite subfamily is independent. When a joint probability density function exists, independence is equivalent to its factorization into the product of the marginal density functions.

See also

Independent Events, Joint Distribution, Random Variable

Explore with Wolfram|Alpha

References

Papoulis, A. Probability, Random Variables, and Stochastic Processes, 2nd ed. New York: McGraw-Hill, 1984.

Cite this as:

Weisstein, Eric W. "Independent Random Variables." From MathWorld--A Wolfram Resource. https://mathworld.wolfram.com/IndependentRandomVariables.html

Subject classifications