Stochastic resetting is the interruption of a stochastic process at random times followed by its return to a specified reset state. In
the standard diffusion model, a particle with diffusion coefficient  is reset to
 at the event times of a Poisson
process with rate
 . Its probability
density function satisfies
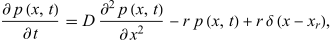 |
(1)
|
where  is the delta function. Unlike ordinary free diffusion,
this process has the stationary density
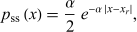 |
(2)
|
where  .
For a target at distance  from the reset point, the mean first-passage
time is
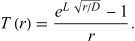 |
(3)
|
It is finite for every  and has a unique minimum
at
 |
(4)
|
where the positive root 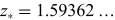 satisfies
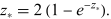 |
(5)
|
Thus resetting too frequently prevents the target from being reached, while resetting too rarely fails to suppress long unsuccessful excursions. Evans and Majumdar (2011) introduced this canonical model, which has since been generalized to non-Poisson reset times, random reset positions, drift, and multiple searchers.