

A Poisson point process on  with a locally finite Borel intensity
measure
 is a random counting measure whose counts in
disjoint Borel sets of finite intensity are independent
random variables with the Poisson distribution.
Here
 is a positive integer, and local finiteness means
 for every bounded Borel set
 . For every Borel
set
 of finite intensity, its count has expectation value
 . Repeated points are allowed at
point atoms, points
 with
 . On
 , a homogeneous process of constant intensity
function
 uses
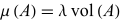 ,
where
 denotes Lebesgue measure. Its law
is invariant under translations. It has almost
surely no repeated points because Lebesgue measure
has no point atoms.
For example, planar Poisson nuclei of intensity  with
 generate the random Voronoi
diagram in Voronoi percolation. The number
of nuclei in a unit square has expectation
value
 ,
whereas cell colors are sampled independently
of these nuclei.
