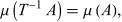TOPICS
Search

Invariant Measure


An invariant measure for a measurable function T:X->X on a measurable space (X,F) is a measure mu satisfying

 mu(T^(-1)A)=mu(A),

where T^(-1)A is the pre-image of any A in F. Equivalently, the pushforward measure T_*mu equals mu. An invariant probability measure makes T a measure-preserving transformation of the corresponding probability space. For example, a rotation T(x)=x+a  (mod1) of R/Z preserves normalized Lebesgue measure. An invariant probability measure is an ergodic measure when every measurable set A satisfying T^(-1)A=A has measure 0 or 1 (Walters 1982; Walkden 2018, pp. 27, 29, and 43-44).
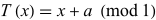


See also

Endomorphism, Ergodic Measure, Ergodic Theory, Koopman Operator, Measure-Preserving Transformation, Mixing Transformation, Probability Measure, Pushforward Measure

Explore with Wolfram|Alpha

References

Walkden, C. Ergodic Theory. Lecture notes for MATH41112/61112, pp. 27-29 and 43-44, Jan. 4, 2018. https://personalpages.manchester.ac.uk/staff/Charles.Walkden/ergodic-theory/ergodic_theory.pdf.Walters, P. An Introduction to Ergodic Theory. New York: Springer-Verlag, 1982.

Cite this as:

Weisstein, Eric W. "Invariant Measure." From MathWorld--A Wolfram Resource. https://mathworld.wolfram.com/InvariantMeasure.html

Subject classifications