

A Gaussian process is a family of random variables whose every finite linear
combination has a normal distribution,
with degenerate distributions allowed. It is determined by its mean function  and covariance function
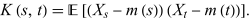 |
For example, if  is standard normal and
 is a deterministic function,
then
 is a Gaussian process with covariance
 . A Gaussian free
field uses an analogous Gaussian family indexed by
test functions. The Gaussian Sherrington-Kirkpatrick
model Hamiltonian is a Gaussian process indexed by spin configurations because
its coefficients are Gaussian and it is linear in those coefficients. Applying nonlinear
functions to Gaussian pattern measurements in a random
perceptron does not generally give a Gaussian process.
