


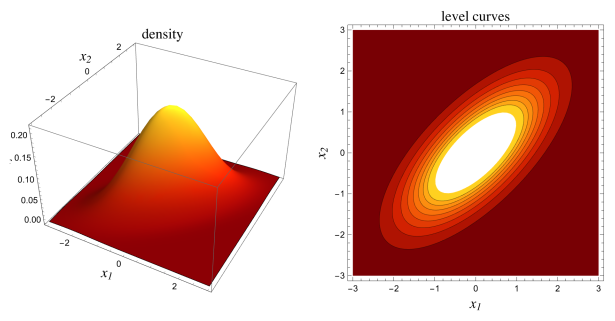
A nonsingular bivariate normal distribution has probability density function
 |
(1)
|
where
 |
(2)
|
and
 |
(3)
|
is the correlation of  and
 (Kenney and Keeping 1951, pp. 92 and 202-205; Whittaker
and Robinson 1967, p. 329) and
 is the covariance.
The bivariate normal distribution is implemented in the Wolfram Language as MultinormalDistribution[mu,
v], where mu is the vector of means  and v is the covariance matrix
 . The coefficients
 used in the derivation below are entries of the matrix
 of a linear transformation,
rather than entries of
 . They satisfy
 , where
 denotes the transpose.
The marginal probabilities are then
 |  |  |
(4)
|
 |  |  |
(5)
|
and
 |  |  |
(6)
|
 |  |  |
(7)
|
(Kenney and Keeping 1951, p. 202).
Let  and
 be two independent normal variates with means
 and
 for
 , 2. Then the variables
 and
 defined below are normal bivariates with unit variance
and correlation coefficient
 :
 |  |  |
(8)
|
 |  |  |
(9)
|
To derive the bivariate normal probability function, let  and
 be normally and independently distributed variates with
mean 0 and variance 1, then
define
 |  |  |
(10)
|
 |  |  |
(11)
|
(Kenney and Keeping 1951, p. 92). The variates  and
 are then themselves normally distributed with means
 and
 ,
variances
 |  |  |
(12)
|
 |  |  |
(13)
|
and covariance
 |
(14)
|
The covariance matrix is defined by
 |
(15)
|
where
 |
(16)
|
Now, the joint probability density function for  and
 is
 |
(17)
|
but from (10) and (11), we have
 |
(18)
|
As long as
 |
(19)
|
this can be inverted to give
 |  |  | |
 |  |  |
(20)
|
Therefore,
 |
(21)
|
and expanding the numerator of (21) gives
 |
(22)
|
so
 |
(23)
|
Now, the denominator of (21) is
 |
(24)
|
so
 |  |  |
(25)
|
 |  |  |
(26)
|
 |  |  |
(27)
|
can be written simply as
 |
(28)
|
and
 |
(29)
|
Writing the determinant as  , the inverse
transformation is
 |  |  |
(30)
|
 |  |  |
(31)
|
The absolute value of the Jacobian is
 |  |  |
(32)
|
 |  |  |
(33)
|
so
 |
(34)
|
and
 |
(35)
|
where
 |
(36)
|
Q.E.D.
The characteristic function of the bivariate normal distribution is given by
 |  |  |
(37)
|
 |  |  |
(38)
|
where
 |
(39)
|
and
 |
(40)
|
Now let
 |  |  |
(41)
|
 |  |  |
(42)
|
Then
 |
(43)
|
where
 |  |  |
(44)
|
 |  |  |
(45)
|
Complete the square in the inner integral
 |
(46)
|
Rearranging to bring the exponential depending on  outside the inner integral, letting
 |
(47)
|
and writing
 |
(48)
|
gives
 |
(49)
|
Expanding the term in braces gives
 |
(50)
|
But  is odd, so the integral over the sine term vanishes,
and we are left with
 |
(51)
|
Evaluating the Gaussian integral
 |  |  |
(52)
|
 |  |  |
(53)
|
for  and real
 gives the explicit form of the characteristic
function,
 |
(54)
|
In the singular case that
 |
(55)
|
(Kenney and Keeping 1951, p. 94), it follows that
 |
(56)
|
 |  |  |
(57)
|
 |  |  |
(58)
|
 |  |  |
(59)
|
 |  |  |
(60)
|
so
 |  |  |
(61)
|
 |  |  |
(62)
|
where
 |  |  |
(63)
|
 |  |  |
(64)
|
For a bivariate normal distribution with  , positive marginal standard
deviations, and correlation coefficient
 ,
the quadrant probability
is given analytically by
 |  |  |
(65)
|
 |  |  |
(66)
|
 |  |  |
(67)
|
(Rose and Smith 1996; Stuart and Ord 1998; Rose and Smith 2002, p. 231). Similarly,
 |  |  |
(68)
|
 |  |  |
(69)
|
 |  |  |
(70)
|
