

A finite absorbing Markov chain is a Markov chain with at least one absorbing state and with a positive probability of eventually reaching an absorbing state from every other state. The transition probabilities are assumed to be independent of time (Grinstead and Snell 1997, p. 416).
Suppose there is at least one nonabsorbing state. Ordering these states first puts the stochastic matrix in the form
 |
(1)
|
where  is an identity matrix of the required size and
the lower-left block is a zero matrix. The submatrix
 records only transitions between nonabsorbing
states, so its row sums can be less than 1.
For a chain starting in a nonabsorbing state  , let
 be the first time it reaches an absorbing
state. Then
 ,
and the matrix inverse
 |
(2)
|
where  now has the same dimensions as
 , gives the expected number
 of visits to nonabsorbing state
 before time
 .
The visit at time 0 is included. Consequently, the expected
number of steps to absorption is
 |
(3)
|
These quantities are finite (Grinstead and Snell 1997, pp. 418-420).
To prove convergence, choose a route to absorption with positive probability from each nonabsorbing state. Finitely many
states give a common bound  on the route lengths and a common lower bound
 on the probability
of absorption within
 steps. The Markov property therefore gives
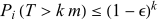 , so
 has finite expectation
and
 .
The identity
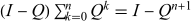 then gives the matrix inverse above. Finally,
 is the probability
of being at nonabsorbing state
 at time
 , so adding the expectations
of the nonnegative visit indicator
functions proves the expected-visit interpretation and the formula for
 . If all states are absorbing, absorption occurs at time
0.
