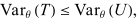TOPICS
Search

Minimum Variance Unbiased Estimator


A minimum variance unbiased estimator of a real parameter theta is an unbiased estimator T with finite variance that has the smallest variance among all unbiased estimators based on the same observations for every admissible value of theta (Lehmann and Casella 1998). Thus, for any other unbiased estimator U of theta,

 Var_theta(T)<=Var_theta(U),

where the subscript indicates the value of the parameter at which the variance is evaluated.

The German tank problem provides an example. A minimum variance unbiased estimator need not exist for every estimation problem.


See also

Estimator, Unbiased Estimator, Variance

Explore with Wolfram|Alpha

References

Lehmann, E. L. and Casella, G. Theory of Point Estimation, 2nd ed. New York: Springer-Verlag, Ch. 2, 1998. https://doi.org/10.1007/b98854.

Cite this as:

Weisstein, Eric W. "Minimum Variance Unbiased Estimator." From MathWorld--A Wolfram Resource. https://mathworld.wolfram.com/MinimumVarianceUnbiasedEstimator.html

Subject classifications