

A Markov shift is the shift on the sequence space of a stationary Markov chain, equipped with its stationary
probability measure. Let  be a countable set of states,
let
 be a stochastic
matrix on
 , and let
 be a stationary statistical
distribution, so that
 . On
 ,
the Markov probability measure
 is specified by
 |
The sigma-algebra is generated by these finite-coordinate sets. The shift is the map
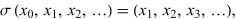 |
and  is an invariant
measure for
 (Walkden 2018, pp. 34-35).
