

A Markov jump linear system is a discrete-time dynamical system that switches among finitely many linear modes according to a Markov
chain. If the mode at time  is
 and the corresponding
 state matrices are
 , then the state evolves according to
 |
(1)
|
Writing  for the stochastic matrix with
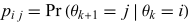 , define
 |  | 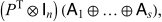 |
(2)
|
 |  | 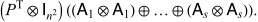 |
(3)
|
Here  denotes the matrix direct sum,
 the Kronecker product,
and
 the
 identity matrix.
The system is mean stable if  for every initial state and mode, and it is mean-square
stable if
 , where
 denotes an expectation value
and
 is a vector norm. It is mean stable iff
 , and it is mean-square stable iff
 , where
 denotes the spectral radius
(Costa and Fragoso 1993).
