

The MUSIC algorithm (multiple signal classification) is a method of spectral estimation that estimates signal parameters from the eigen decomposition of a covariance matrix. It exploits the orthogonality between a signal subspace and a noise subspace (Schmidt 1986, pp. 277-278).
Consider the model
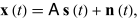 |
(1)
|
where  ,
 ,
 , and the columns of
 are known vectors
 , ...,
 evaluated at unknown parameters.
Assume
 and
 have zero mean, are uncorrelated,
and have covariance matrices
 and
 , respectively, where
 and
 is the identity matrix.
Then
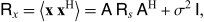 |
(2)
|
where  denotes expectation value and the superscript
H denotes conjugate transpose. If
 has matrix rank
 and
 is positive definite,
the eigenvectors corresponding to the
 largest eigenvalues of
 span
the signal subspace. The remaining
 eigenvectors have eigenvalue
 and span
its orthogonal complement, the noise subspace.
Let  have orthonormal columns spanning
the noise subspace. The defining relation
 |
(3)
|
for  ,
...,
 leads to the MUSIC pseudospectrum
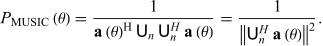 |
(4)
|
In practice, the covariance matrix is estimated from observations and the parameters are estimated
from the largest peaks of  . Unique recovery additionally requires that no other
parameter value produce a vector
 in the signal subspace.
The pseudospectrum is a parameter-location criterion rather than an estimate of signal
power (Schmidt 1986, pp. 277-279; Stoica and Nehorai 1989, pp. 721-723).
For frequency estimation, one uses
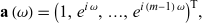 |
(5)
|
where  is measured in radians per sample and the superscript
T denotes transpose. Xie and Mo (2026) apply MUSIC
to selecting poles for expansions using Takenaka-Malmquist
systems.
