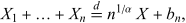TOPICS
Search

Index of Stability


The index of stability is the shape parameter alpha, with 0<alpha<=2, of a nondegenerate stable distribution. It is also called the stability index or characteristic exponent. If X_1, ..., X_n are statistically independent copies of a random variable X with this stable distribution, then

 X_1+...+X_n=^dn^(1/alpha)X+b_n,

where b_n is a constant and equality denotes equality of statistical distributions (Nolan 2020).

The case alpha=2 gives a normal distribution, while alpha=1 with skewness parameter beta=0 gives a Cauchy distribution. For 0<alpha<2, at least one tail probability decays as a positive constant times x^(-alpha) as x->infty, and the variance is infinite (Nolan 2020).

See also

Cauchy Distribution, Characteristic Exponent, Normal Distribution, Shape Parameter, Skewness Parameter, Stable Distribution

Explore with Wolfram|Alpha

References

Nolan, J. P. Univariate Stable Distributions: Models for Heavy Tailed Data. Cham, Switzerland: Springer, 2020. https://doi.org/10.1007/978-3-030-52915-4.

Cite this as:

Weisstein, Eric W. "Index of Stability." From MathWorld--A Wolfram Resource. https://mathworld.wolfram.com/IndexofStability.html

Subject classifications