

Importance sampling is a Monte Carlo method which samples from an alternative probability
density function and reweights the observations to estimate an expectation
under the target statistical distribution.
If the target and sampling probability
density functions are  and
 , respectively, the estimator is
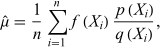 |
where the  are independent and identically
distributed with density
 . If
 wherever
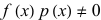 and
 is integrable under
 , this is an unbiased estimator
of
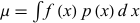 (Owen 2013). A well-chosen
 can reduce the variance, but
an inappropriate choice can increase it.
