The Gram-Charlier A series is a formal expansion of a probability density function  around the standard normal
distribution density
 in Hermite polynomials.
In one common normalization, it has the form
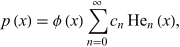 |
where
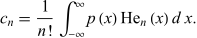 |
For a standardized random variable, 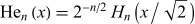 and
 , while the higher coefficients can be expressed in
terms of its moments or cumulants.
A truncated Gram-Charlier A series need not be nonnegative and therefore need not itself be a probability density function; convergence also requires additional hypotheses. The Edgeworth series uses related terms but reorders them according to their asymptotic dependence on sample size, so the two series are not synonyms.