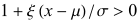TOPICS
Search

Generalized Extreme Value Distribution


The generalized extreme value distribution is the family of continuous probability distributions with cumulative distribution function
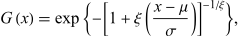
 G(x)=exp{-[1+xi((x-mu)/sigma)]^(-1/xi)},

defined where 1+xi(x-mu)/sigma>0, with location parameter mu, scale parameter sigma>0, and shape parameter xi. The limiting case xi=0 is the Gumbel distribution; positive and negative shape parameters give the Fréchet and reversed Weibull types, respectively. These are the possible nondegenerate limiting distributions for suitably normalized maxima.

See also

Extreme Value Distribution, Extreme Value Theory, Fréchet Distribution, Gumbel Distribution

Explore with Wolfram|Alpha

References

de Haan, L. and Ferreira, A. Extreme Value Theory: An Introduction. New York: Springer-Verlag, 2006.

Cite this as:

Weisstein, Eric W. "Generalized Extreme Value Distribution." From MathWorld--A Wolfram Resource. https://mathworld.wolfram.com/GeneralizedExtremeValueDistribution.html

Subject classifications