

A Gaussian measure on Euclidean space is a probability measure for which every linear
combination of its coordinates has a normal
distribution, allowing constant combinations in
the degenerate case. The standard Gaussian measure  on
 has mean zero,
covariance matrix equal to the identity
matrix, and probability density function
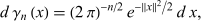 |
where  is the Euclidean norm. The random
variables given by its coordinates are independent,
each with a standard normal distribution.
