

The finite difference is the discrete analog of the derivative. The finite forward difference of a function  is defined as
 |
(1)
|
and the finite backward difference as
 |
(2)
|
The forward finite difference is implemented in the Wolfram Language as DifferenceDelta[f, i].
If the values are tabulated at spacings  , then the notation
 |
(3)
|
is used. The  th
forward difference would then be written as
 , and similarly, the
 th backward difference
as
 .
However, when  is viewed as a discretization of the continuous
function
 , then the finite difference is sometimes written
 |  |  |
(4)
|
 |  | *f(x),](/images/equations/FiniteDifference/Inline14.svg) |
(5)
|
where  denotes convolution and
](/images/equations/FiniteDifference/Inline16.svg) is the odd impulse pair. The finite difference
operator can therefore be written
 |
(6)
|
An  th
power has a constant
 th finite difference. For example, take
 and make a difference table,
 |
(7)
|
The  column is the constant 6.
Finite difference formulas can be very useful for extrapolating a finite amount of data in an attempt
to find the general term. Specifically, if a function  is known at only a few discrete values
 , 1, 2, ... and it is desired to determine the analytical
form of
 , the following procedure can be used if
 is assumed to be a polynomial
function. Denote the
 th value in the sequence of interest
by
 . Then define
 as the forward difference
 ,
 as the second forward
difference
 , etc., constructing
a table as follows
 |
(8)
|
 |
(9)
|
 |
(10)
|
 |
(11)
|
Continue constructing the difference table through the last available row. The unique polynomial of degree at most  interpolating the
 values
 ,
 , ...,
 is then given by
 |  |  |
(12)
|
 |  |  |
(13)
|
Here  , so
 ,
 , etc. This equation
is called Newton's forward difference
formula. To see a particular example, consider a sequence
with first few values of 1, 19, 143, 607, 1789, 4211, 8539, .... The difference
table is then given by
 |
(14)
|
Reading off the first number in each row gives  ,
 ,
 ,
 ,
 . Plugging these in gives the equation
 |  |  |
(15)
|
 |  |  |
(16)
|
which indeed fits the original data exactly.
Formulas for the derivatives are given by
 |  |  |
(17)
|
 |  |  |
(18)
|
 |  |  |
(19)
|
 |  |  |
(20)
|
 |  |  |
(21)
|
 |  |  |
(22)
|
 |  |  |
(23)
|
 |  |  |
(24)
|
 |  |  |
(25)
|
 |  |  |
(26)
|
 |  | 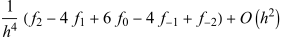 |
(27)
|
(Beyer 1987, pp. 449-451; Zwillinger 1995, p. 705).
Formulas for integrals of finite differences
 |
(28)
|
are given by Beyer (1987, pp. 455-456).
Finite differences lead to difference equations, finite analogs of differential equations. In fact, umbral calculus displays many elegant analogs of well-known identities for continuous functions. Common finite difference schemes for partial differential equations include the Crank-Nicolson method, Du Fort-Frankel method, and Laasonen method.
Numerical differentiation formulas use weights that can be generated from Taylor series on equally spaced nodes, or from derivatives of Lagrange interpolating polynomials on arbitrary distinct nodes. Recursive constructions provide weights for several derivative orders at once. Accurate weights do not prevent cancellation when a high-order derivative formula is applied to approximate data (Fornberg 1998).
