

A variance component is a parameter representing the contribution of a random effect to the total variance in a statistical model. For the random-intercept model
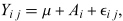 |
with independent  and
 having variances
 and
 , respectively, the marginal variance of an observation
is
 . The two summands are variance components.
Observations sharing the same random effect are correlated. In the example, two observations in the same group have covariance  . Variance components
are estimated in random effects models, often
by maximizing an ordinary or restricted likelihood
function.
