

Stochastic dominance is an ordering of statistical distributions in which one random variable
is at least as likely as another to exceed every threshold. In the usual stochastic
order, a real-valued random variable  stochastically dominates
 iff
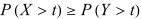 |
for every real number  . Equivalently, their distribution
functions satisfy
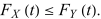 |
The inequality concerns statistical distributions, so it does not require  for each outcome in a particular joint realization (Shaked
and Shanthikumar 2007).
Stochastic dominance implies 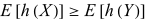 for every increasing function
 for which the two expectation
values exist. In particular, it implies the same ordering of their expectation
values, but that ordering alone is insufficient. For example, a random
variable taking 0 and 2 with equal probability
and the constant 1 have the same expectation value,
but neither stochastically dominates the other.
