Stochastic continuity of a stochastic process  taking values in Euclidean
space
 means that
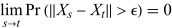 |
for all  and
 , with
 . Here,
 is the Euclidean norm
and
 denotes probability. It is also called continuity
in probability (Sato 1999, p. 3).
 TOPICS

Stochastic continuity of a stochastic process taking values in Euclidean
space
means that
|
for all and , with . Here, is the Euclidean norm
and
denotes probability. It is also called continuity
in probability (Sato 1999, p. 3).

Weisstein, Eric W. "Stochastic Continuity." From MathWorld--A Wolfram Resource. https://mathworld.wolfram.com/StochasticContinuity.html