TOPICS
Search

Stochastic Approximation


Stochastic approximation is a family of iterative methods for finding a root or optimum when observations are corrupted by noise. A typical recursion has the form
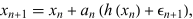
 x_(n+1)=x_n+a_n(h(x_n)+epsilon_(n+1)),

where a_n is a decreasing step size, h is the mean update, and epsilon_(n+1) is a noise term. Standard convergence hypotheses include sum_(n)a_n=infty and sum_(n)a_n^2<infty together with stability and suitable control of the noise.

The Robbins-Monro stochastic approximation estimates a root of a regression function, while stochastic gradient methods use noisy estimates of the gradient of an objective function.

See also

Method of Steepest Descent, Robbins-Monro Stochastic Approximation, Stochastic Optimization

Explore with Wolfram|Alpha

References

Kushner, H. J. and Yin, G. G. Stochastic Approximation and Recursive Algorithms and Applications, 2nd ed. New York: Springer-Verlag, 2003.Robbins, H. and Monro, S. "A Stochastic Approximation Method." Ann. Math. Stat. 22, 400-407, 1951. https://doi.org/10.1214/aoms/1177729586.

Cite this as:

Weisstein, Eric W. "Stochastic Approximation." From MathWorld--A Wolfram Resource. https://mathworld.wolfram.com/StochasticApproximation.html

Subject classifications