

A self-decomposable distribution is a statistical distribution such that, for every  ,
a random variable
 with that distribution can be represented in distribution
as
 , where
 has the same distribution as
 and is independent of
 (Schilling et al. 2012). Every self-decomposable
distribution is an infinitely divisible
distribution.
For a strictly positive probability density function  on
 ,
Mao and Tian (2026) proved that logarithmic convexity together with geometric concavity
is sufficient for self-decomposability. Here logarithmic convexity means that
 is convex, and geometric concavity means that
 is concave. For
differentiable
 ,
the latter condition is equivalent to
 being nonincreasing. The conditions are sufficient
and need not describe the entire parameter range of self-decomposable laws. The same
authors proved that if
 is logarithmically convex and
 is nondecreasing, then a random
variable with density
 has the distribution of
 , where
 has density
 and
 is independent of
 .
For the Whittaker density proportional to 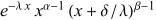 on
 , where
 ,
these criteria prove self-decomposability when
 and
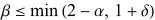 .
They also give an independent nonnegative additive remainder when
 and
 are increased by arbitrary nonnegative amounts from a starting
pair with
 and
 (Mao and Tian 2026).
