Ordinary least squares is a method for estimating the coefficient vector in a linear regression model by minimizing the unweighted
sum of squared residuals. For a design matrix  and response vector
 , the estimate
 minimizes
 |
It therefore satisfies the normal equations
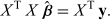 |
When the columns of  are linearly independent,
the estimate is unique. In contrast, weighted and generalized least squares modify
the residual norm to account for unequal variances or correlated errors.