

The term "Jacobi matrix" has several meanings in mathematics.
One meaning is the matrix of first partial derivatives of a vector function, also called a Jacobian. The Jacobian determinant is its determinant when the matrix is square.
The term is also used for a Jacobi rotation matrix.
Another meaning is a tridiagonal matrix that encodes the three-term recurrence relation for a family of orthogonal polynomials. For orthogonal polynomials normalized as orthonormal functions with positive leading coefficients, the Jacobi matrix is the real symmetric matrix
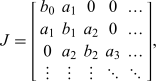 |
(1)
|
where  is real and
 for
 . The corresponding orthonormal polynomials satisfy
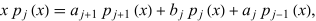 |
(2)
|
where  and
 . With a different normalization, the two off-diagonal
sequences need not be equal. Favard's theorem
gives the positive measure associated with these
coefficients.
Let  be the leading
 block of
 . If
 is the monic polynomial
proportional to
 , then
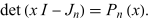 |
(3)
|
Thus the eigenvalues of  are the zeros of
 . They are real and
distinct, and the zeros of consecutive orthogonal
polynomials interlace. For unit eigenvectors
 corresponding to eigenvalues
 , the weights of Gaussian
quadrature are
 |
(4)
|
where  is the total mass of the measure. This is the matrix
method of Golub and Welsch (1969, pp. 221-223).
