The Gauss-Markov theorem states that the ordinary least squares estimator is the best linear unbiased estimator in a linear regression model with uncorrelated errors of equal variance. Here an estimator is a rule for estimating an unknown parameter from data in a sample. Linear means linear in the observations, unbiased means that its expectation value equals the parameter, and best means that it has the smallest variance among the linear unbiased estimators.
More precisely, suppose
 |
(1)
|
where  has full column rank,
 , and
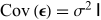 . Then
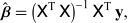 |
(2)
|
is unbiased, and for every other linear unbiased estimator  ,
the matrix
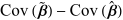 |
(3)
|
is positive semidefinite. No normal distribution assumption is needed for this conclusion.